10 money mistake that keep you broke and proven ways to avoid them
Living paycheck to paycheck? These 10 common money mistakes keep you broke — plus proven, practical ways to avoid them and start saving.
Three days before payday, I checked my bank app and saw ₦1,450. Not ₦14,500. Just one thousand four hundred and fifty naira.
I wasn't buying luxury stuff or flexing in the club. Money was just leaking away in tiny places I kept ignoring, quick data top-ups, bank transfer fees, random takeout, one loan app I promised myself I'd use "just once," and that sweet lie we all tell ourselves: "I'll save proper money next month."

The things that drain your account are rarely dramatic. They hide behind excuses like "it's just ₦2,000," "I deserve a treat," and "my salary is too small to save anyway." I'm not a financial consultant giving official advice. I am someone who has made almost all these mistakes, felt the embarrassment, and figured out what actually helps you survive and build stability in real Nigerian conditions.
You don't need a seven-figure income to start turning things around. You just need to block a couple of leaks. Choose one item here and fix it this week. That's all it takes to get started.
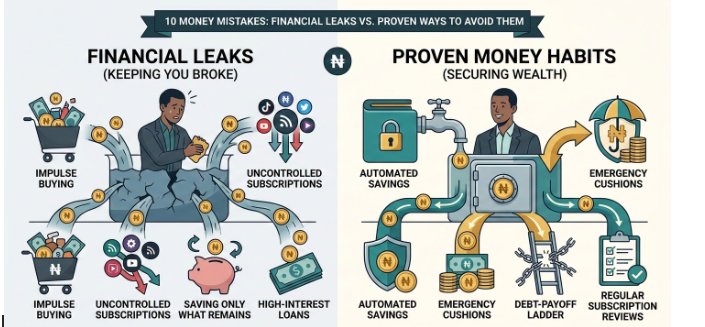
1. Saving only what happens to remain at the end of the month
This trapped me for years. I'd leave whatever was left on the 30th for savings, but usually, nothing was left. If I did move ₦5,000 aside, I'd end up pulling it back before the mid-month mark. Savings was basically just a holding spot for cash I was about to spend anyway.
What worked was setting up an automatic debit the moment my salary dropped. Even if it's ₦2,000 or ₦5,000, send it straight to a separate account or piggybank app that locks your funds. If you don't see it sitting in your main spending account, you adjust automatically without stressing.
Starting with ₦2,000 on an ₦80,000 salary might feel insignificant, but building the habit matters far more than trying to force a huge amount you can't maintain.

2. Treating impulse buying like part of your personality
I used to tell people "I'm just terrible with money" like it was unchangeable. But spending impulsively usually happens because of specific triggers: late-night scrolling through IG vendors, ordering a ride service because you're tired, or stepping into the market for one item and leaving ₦15,000 poorer.
Give non-essential purchases a mandatory 24-hour waiting period. Put the item in your cart, then close the app. Most times, the urge passes by the next day. Another practical step: remove your debit card details saved on shopping platforms. Forcing yourself to type out 16 digits every time slows you down enough to rethink.
3. Normalizing high-interest short-term loans
Loan apps, bank overdrafts, and borrowing ₦5,000 here and there from friends can quietly ruin your finances. The interest rates and rollover fees pile up, eating away your upcoming income before it even arrives.
Pick one clear debt-payoff plan. You can tackle the balance with the highest interest first to save money, or pay off the smallest balance first to clear easy wins and feel like you're making progress. I went with the smallest debt first because I needed quick relief. The key is to completely stop taking new loans while clearing old ones. Delete the loan apps off your phone if you have to.

4. Making your budget so strict that you hate it
People ditch budgets because they treat them like a punishment. If your plan allows zero room for enjoying life, you'll abandon it by the second week.
Don't bother with fancy spreadsheets at first. Just log everything you spend in your notes app for seven days. Seeing where your money goes opens your eyes fast. From there, split your income into three clear parts: essentials (rent, food, transport), savings, and personal fun money. Including money for enjoyment keeps you from quitting the system.
5. Letting your expenses rise automatically every time your income increases
You get a pay rise, and suddenly your current phone seems too old, your apartment feels inadequate, and your eating habits change overnight. You end up earning more money but feeling just as broke as before.
Decide where extra money goes before your new salary lands. Direct a big chunk of any raise toward savings or clearing debts first. If your monthly income goes up by ₦50,000, don't instantly take on a bigger apartment that eats the whole ₦50,000. Upgrade your life slowly and intentionally.
6. Operating with zero financial cushion for emergencies
Unexpected expenses always show up: car repairs, family health issues, or sudden price hikes on daily transport. Without cash tucked away, your only option is borrowing, which sends you right back into debt.
Build a starter emergency fund of ₦50,000 first. That amount alone can absorb minor surprises without pushing you into panic mode. Work your way up toward saving three to six months of essential living costs. Keep this money in a separate account so you aren't tempted to use it for random weekends out.

7. Ignoring retirement contributions because it feels too far away
Retirement feels like a problem for decades down the line. But starting early makes a massive difference because compound interest needs time to work properly. Delaying by ten years means you'll have to contribute far more every month to catch up.
If your job offers a pension account (RSA) under the Contributory Pension Scheme, check regularly to confirm your employer actually pays in your deductions. If you can afford an additional voluntary contribution, even just 1% or 2% of your salary, set it up to deduct automatically.
8. Using spending as emotional relief
A rough day at work or an argument often leads straight to buying things online or ordering expensive food just for a quick mood boost.
Notice what feelings push you to buy. Are you bored, stressed, or angry? When that urge hits, force a 20-minute pause. Step away, grab water, or call a friend. Usually, the impulse fades once your mood cools down.
9. Letting monthly subscriptions quietly drain your funds
Small recurring payments add up fast: ₦2,200 for TV streaming, ₦900 for music, ₦1,500 extra data passes, plus gym memberships you barely use. Because each charge looks minor individually, they go unmonitored for months.
Review your bank statement every few months. Highlight every recurring bill and ask yourself if you actually used it in the last 30 days. Cancel anything that isn't serving you right now. You can always resubscribe later if you miss it.
10. Leaving all your money in standard savings accounts
Saving money is important, but leaving extra cash in a basic bank account means inflation slowly erodes its real value over time.
You don't need complex stock trading knowledge to begin. Look into straightforward options like money market funds, mutual funds, or Treasury bills through reputable financial institutions. Avoid high-risk schemes or get-rich-quick tips from social media chat groups. Focus on steady, reliable returns.
Final thoughts
Gaining financial control isn't about waiting for a massive pay jump. It's about stopping money leaks, automating good habits, recognizing emotional spending triggers, and making steady progress over time.
You don't lack financial ability; you just need better habits in place. Pick one area to address this week, fix it, and move on to the next. Small improvements add up faster than you think.
Frequently Asked Questions
What's Your Reaction?
 Like
1
 Dislike
0
 Love
1
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Comments (0)